Home Pre Launches Residential Properties Commercial Properties Black Circle Refer a Client Why Us Meet Our Team Awards & Recognitions Blog Call Us Terms & Conditions

+91 636 44 66 801  ·  Bengaluru · Hyderabad · Gurgaon · Dubai

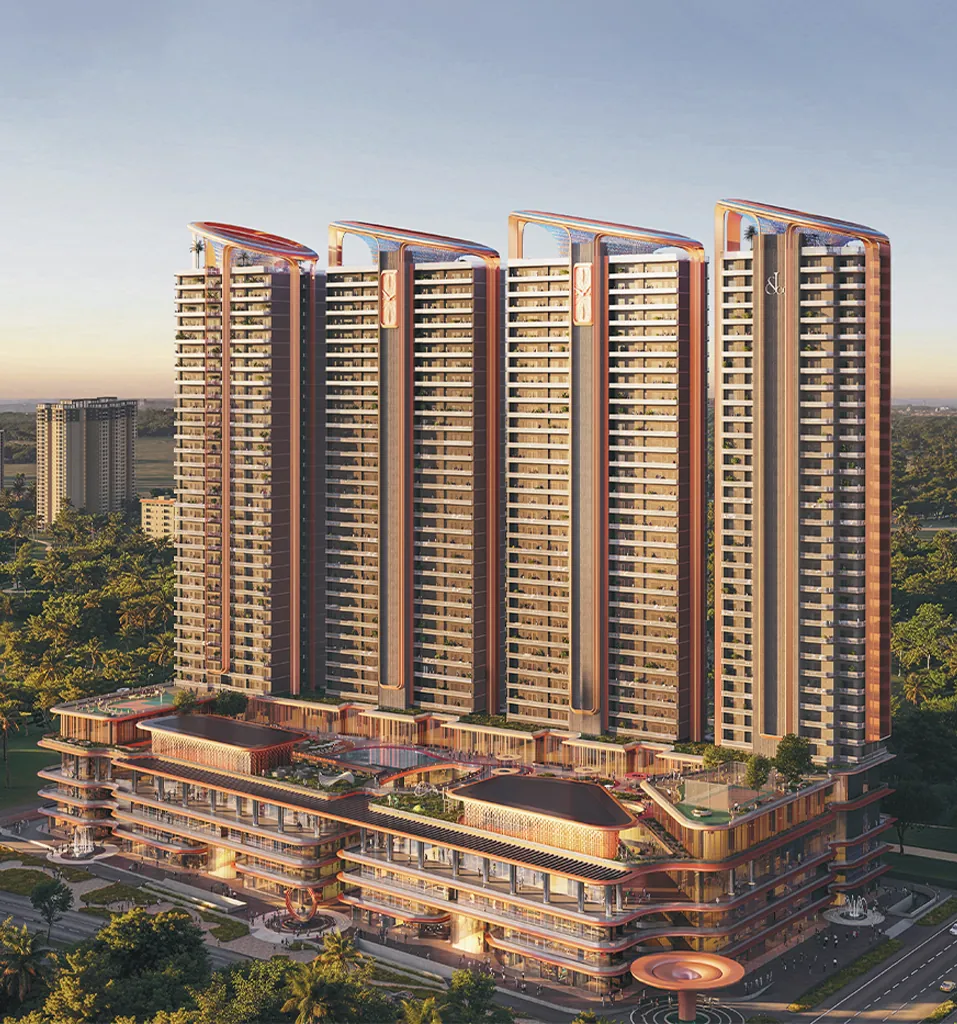
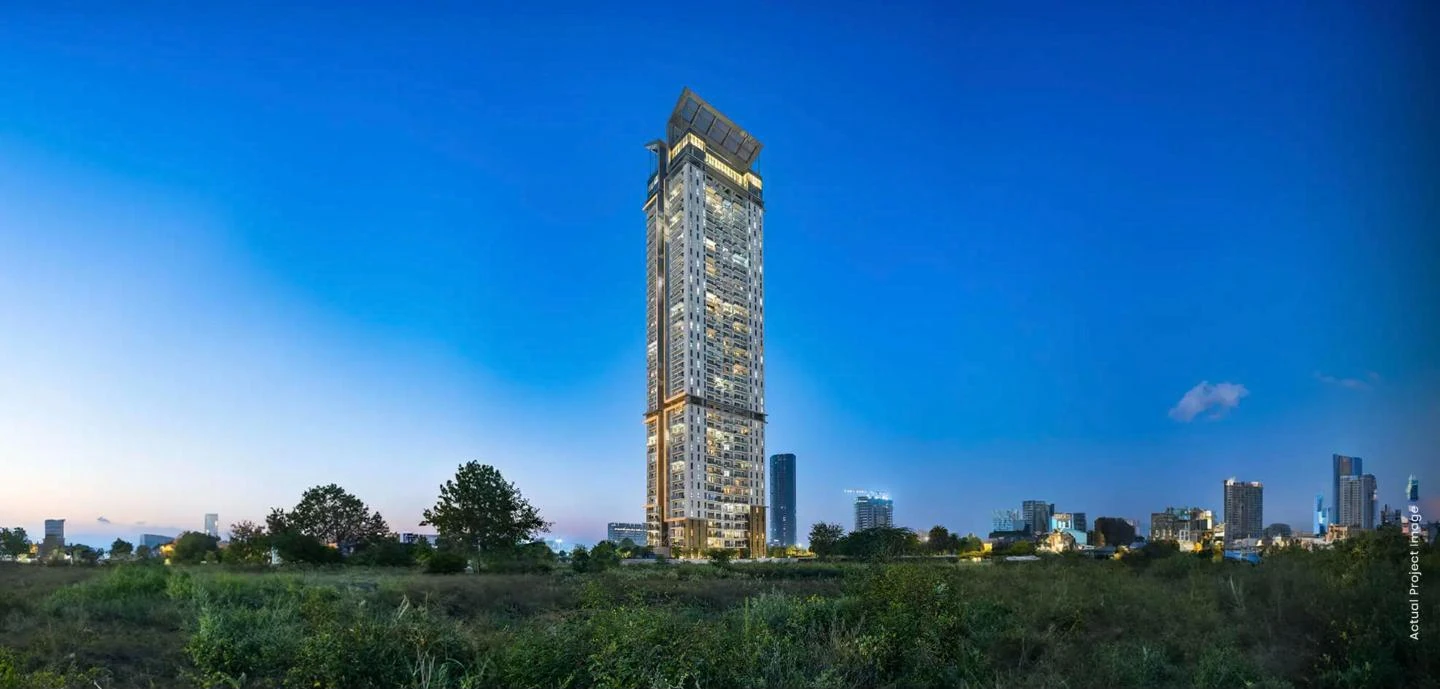
The Westin Residences, Dwarka Expressway, Gurgaon — illuminated arrival court at dusk
Luxury Real EstateBengaluru · Hyderabad · Gurgaon · Dubai

Discover the clarity in Real Estate.

A research-led advisory for buyers who treat an address as a long-term position, not a purchase. Every conversation is private, every mandate handled by a single dedicated relationship manager.

Explore residences
Scroll
SobhaLodhaEmbassy GroupM3M IndiaMAIA EstatesMSN RealtyCentury Real EstateSobhaLodhaEmbassy GroupM3M IndiaMAIA EstatesMSN RealtyCentury Real Estate
What we do

Research first.
Recommendation second.

Bridgekeys exists to help discerning buyers discover exceptional properties — guided by trusted real-estate expertise, carefully curated opportunities, transparent counsel, and a genuinely premium experience at every step.

We build long-term relationships, not transactions. Every recommendation is grounded in diligence. Every address we represent is chosen with the same discernment we ask our clients to bring to their own decisions.

B Lounge interior of a curated residence
0Curated developments
0Relationship manager per client
0Cities represented
0Top of the price band
Handled privately

Discretion is the
first service.

Consultations are held by appointment and in private — at our office, at the site, or wherever suits you. Your name, budget and holdings are never circulated to developers as a lead, never sold, and never used in marketing. Where a booking requires disclosure to a developer, we tell you exactly what is being shared before it goes.

By appointment only

Every conversation
happens in private.

One dedicated relationship manager. No shared floor, no queue behind you, no details passed on. We meet at our office, at the site, or over video if you are buying from abroad.

AB
“I had a great experience with Bridgekeys. The team is professional, transparent, and genuinely focused on helping clients find the right property. I highly recommend them to anyone looking for a luxury real estate company in Bangalore.”
Ashish Kumar Barman · 4 BHK, Sobha One World
Book an appointment

A private
consultation.

Tell us the shape of what you're looking for. A dedicated relationship manager responds within one working day with a shortlist, a pricing view and available site-visit slots — held in confidence, with no mass mailers and no call-centre follow-up.

Prefer to talk now

+91 636 44 66 801
Your request is emailed straight to a relationship manager and held in confidence. Prefer to message? WhatsApp us on +91 636 44 66 801.
From the blog

Market notes,
written plainly.

Read the blog
Gurgaon · Market Trends

A third of new Gurgaon homes now cost over ₹2.5 crore. What if your budget is below that?

NCR is simultaneously India's most luxury-weighted market and one that still launches a third of its homes at the bottom. The squeeze is in the middle, where most buyers actually are.

ANAROCK's Q3 2026 numbers describe an NCR market shaped like a barbell. Of everything launched in the quarter, 62% was priced above ₹1.5 crore and 34% above ₹2.5 crore — the highest luxury and ultra-luxury share of any of India's top seven cities. At the same time 33% of launches sat in the affordable and lower-mid bands. Weight at both ends, and comparatively little between them.

Hold that against Bengaluru, which launched 52% of its homes above ₹1.5 crore and just 1% in the affordable and lower-mid bands. Bengaluru has effectively stopped building at the bottom. NCR has not — it has kept a third of its supply there while simultaneously pushing a third into the ₹2.5 crore-plus band. These are two genuinely different market structures, and they call for different buying strategies even though the headline price per square foot is similar: ₹9,980 in NCR against ₹9,600 in Bengaluru.

If your budget is ₹1.5 to ₹2.5 crore in Gurgaon, the arithmetic puts you in the thinnest part of the distribution — roughly 28% of launches, between the 62% above ₹1.5 crore and the 34% above ₹2.5 crore. You are not priced out, but you are shopping in the band where developers are launching least, and that shows up as less choice, fewer launch-stage incentives and slower movement on price than buyers one band above are being offered.

Geographically that supply sits where the land is newer: the New Gurgaon sectors, the Dwarka Expressway corridor and parts of the Southern Peripheral Road. It is worth knowing that the Haryana government's own April 2026 collector rate revision raised the circle rates in Sectors 104 to 115 by about 62 to 67%, against 10 to 20% on Golf Course Road. The state does not revise rates on a hunch; a revision of that size is a statement that recorded transaction values in those sectors have moved and the official rate had fallen behind.

That leaves three workable approaches. Buy in the repricing corridor and accept that you are taking infrastructure timing risk in exchange for entry price — the roads and the metro extensions are partly ahead of you, not behind you. Or buy resale in an established sector, where ₹2.5 crore buys a larger or better-positioned home than the same money buys new, at the cost of an older building and a less complete amenity set. Or stretch into the bottom of the luxury band, where developer discipline and build quality are more consistent and where, perversely, there is more to choose from.

What not to do is wait for the band to refill. NCR posted 12% year-on-year price growth in Q3 2026, the fastest of any major Indian market, against 10,900 launches and 13,750 units sold — a market selling more than it is launching. Inventory stands at 86,200 homes with an 18-month overhang, which is healthy rather than distressed. There is no supply wave coming to rescue the middle of this market.

The counterweight, and it is a real one: an 18-month overhang means you are not forced to decide this week either. There are 86,200 unsold homes in NCR. Take the site visits, compare the cost sheets properly, and treat any launch-day urgency as a sales technique rather than a market condition. In our experience the ₹1.5–2.5 crore buyer who moves deliberately over six weeks does materially better than the one who books on the first visit.
Full article ↗
Bengaluru · Market Trends

Bengaluru's unsold stock rose 35% — and it still has India's shortest inventory overhang

The two most alarming-sounding numbers in Bengaluru's quarter contradict each other. Reading them together is the whole skill.

Two figures from ANAROCK's Q3 2026 data describe Bengaluru, and taken separately they tell opposite stories. Unsold inventory reached 80,200 homes, up 35% year on year — the sharpest annual build-up of any city in India's top seven. Inventory overhang stood at 15 months — the shortest of any city in India's top seven. Both are accurate. Neither is the whole picture.

The resolution is in how overhang is calculated: it is unsold stock divided by the rate at which that stock is selling. Bengaluru's inventory grew quickly because the city is launching a great deal — 17,700 homes in Q3 alone, up 16% year on year. But sales grew too, reaching 16,650 units, up 9% on the previous quarter and 12% year on year. A market that launches 17,700 and sells 16,650 in the same quarter is not accumulating dead stock; it is running a large operation at near-balance.

For contrast, look at Hyderabad in the same quarter: 1,14,700 unsold homes and a 28-month overhang, nearly double Bengaluru's, on 12,950 sales. That is what a genuine supply problem looks like. Bengaluru's 80,200 unsold homes clear in a little over a year at current velocity. Hyderabad's take nearly two and a half.

What this means at the negotiating table is narrower than the 35% figure suggests. Fifteen months of overhang gives you choice, not leverage. You will find several comparable options in most corridors and you should use them to compare cost sheets properly — but you should not walk in expecting distress pricing, because the seller's position is not distressed. Average Bengaluru pricing rose 8% year on year to ₹9,600 per square foot in the same quarter the inventory figure jumped.

The composition of that inventory matters as much as its size. Just 1% of Bengaluru's Q3 launches fell in the affordable and lower-mid bands, while 52% were priced above ₹1.5 crore. The stock building up is overwhelmingly premium stock. So the choice a buyer gets is real in the ₹1.5 crore-plus segment and close to non-existent below it — which is the opposite of NCR, where 33% of launches sat in the affordable and lower-mid bands.

One figure worth watching into 2027. Launches fell 18% quarter on quarter, from 21,700 in Q2 to 17,700 in Q3. If developers keep moderating while sales hold near 16,650, the overhang tightens from an already-low base and the 8% price growth has room to continue. If launches resume at Q2 levels while sales stay flat, the 35% inventory build becomes the more important number. Right now the first scenario looks more likely, but it is a quarter-by-quarter question rather than a settled trend.

Our working position: Bengaluru in late 2026 is a well-supplied market with healthy absorption, not a market turning over. Negotiate hard in the eastern and south-eastern corridors where launches concentrate, because that is where the 80,200 actually sits. Do not expect to negotiate in the established core, where nothing is being launched and the inventory figure is irrelevant. And treat 15 months of overhang as what it is — the healthiest number in the country, reported in the same breath as the scariest one.
Full article ↗
Bengaluru · Market Trends

Why Bengaluru developers are buying 50-acre parcels again

After years of eight- and ten-acre infill, three developers have committed township-scale land in a single launch window. The reason is not sentiment about open space.

Within a few weeks of each other, three Bengaluru projects have come to market on parcels that would have looked out of fashion two years ago. Brigade registered a 40-acre township off Whitefield–Kadugodi Road. My Home Group, crossing over from Hyderabad for the first time, has a 52-acre mixed-use parcel at Whitefield Annex. Sobha has entered expression-of-interest activity on roughly 50 acres on Hennur Main Road. After a long run of eight- and ten-acre infill projects, township scale is back.

The reason is mostly arithmetic. Buyer expectations at the ₹1.5 crore-plus level now include a clubhouse of 25,000 square feet or more, substantial open space, multiple sports facilities and a retail component inside the gates. None of that fits on eight acres alongside enough saleable area to pay for the land. Once the amenity programme reaches a certain size, the only parcels that can carry it are at the edge of the city — which is why all three of these sit on the outer corridors rather than in the established core.

What makes these particular parcels work is that they are not merely at the edge; they are on employment corridors. The two Whitefield sites serve ITPL and the eastern technology cluster, which took 61% of Bengaluru's office leasing on the Outer Ring Road axis alone. Hennur serves north Bengaluru and the airport corridor. A fifty-acre parcel with no employment within reach is a land bank, not a township, and the distinction shows up in resale depth a decade later.

The market context explains the timing. Bengaluru launched 17,700 homes in Q3 2026 with 52% priced above ₹1.5 crore and just 1% in the affordable and lower-mid bands, at an average of ₹9,600 per square foot, up 8% year on year. Premium is where the supply is going, and premium at volume needs land. Unsold inventory of 80,200 homes against a 15-month overhang says the city can still absorb it — the shortest overhang in the country.

For a buyer, scale cuts both ways and it is worth being clear about the second edge. A township gives you open space and an amenity set that a small project cannot fund, plus a master plan that protects your outlook from whatever gets built next door. It also means buying into a site that will be under construction around you for years. If you purchase in Phase 1 of a 52-acre development, Phase 3 is still a building site when you move in, and the clubhouse may be scheduled with a later phase than your tower.

So the questions to ask at township scale are specific ones. Which phase is your tower in, and what is committed to complete alongside it? Does the clubhouse land with your phase or a later one? What is the total planned density across all phases, not just the one being sold to you? Where does construction traffic enter, relative to your block? And is the land a single contiguous parcel with clean title, or an assembly that is still being completed? These are answerable questions and a serious developer will answer them in writing.

One caution that applies right now, and it is the reason to read all three of these differently. [Brigade Autograph](?property=brigade-autograph) is registered with Karnataka RERA, which means it is a filed project you can lawfully buy today. [My Home Codename Anandam](?property=my-home-codename-anandam) is at codename stage with no registration issued. Sobha's Hennur township is at expression-of-interest stage, also unregistered. Under the RERA Act a project cannot be booked or sold before registration — so of these three township-scale options, only one is actually purchasable this week. The other two are positions to understand now and act on when the filings appear.

Full article ↗
Google reviews

Bought with us?
Tell the next buyer.

Reviews on our Google Business Profile help other buyers decide whether we are the right advisor for them. If we have helped you — or fallen short — an honest review takes a minute and says more than anything we could write about ourselves.

Call us WhatsApp us